Debts don’t disappear: mapping liabilities in your estate plan
Estate planning usually focuses on what you own. But mortgages, loans, guarantees and tax bills shape what your family actually receives. How to map liabilities so heirs can decide with clear eyes.
When someone dies, their debts generally remain and are settled from the estate before heirs receive anything; in some systems, heirs who accept an inheritance outright can become liable for debts beyond its value. Mapping liabilities — mortgages, loans, credit lines, tax, personal guarantees given for others, and the insurance that may cover them — lets your family see the net picture, claim borrower insurance, and choose the right option for accepting or refusing the estate.
- Your heirs inherit a balance sheet, not just a list of assets.
- Borrower insurance attached to loans is easy to forget and can repay significant sums.
- Personal guarantees given for a business or relative are the most dangerous hidden debts.
- A clear liability map supports the decision to accept or refuse an inheritance.
Nobody enjoys listing debts. But for your family, an unknown liability is worse than a known one: it can surface months later, upset a settlement already agreed, or make heirs regret accepting an estate. Mapping liabilities is an act of protection.
The liability map
| Liability | What to record | Possible cover |
|---|---|---|
| Mortgage | Lender, contract number, outstanding balance, linked property | Borrower insurance |
| Consumer loans & credit cards | Lender, balance, monthly payment | Payment-protection insurance, card cover |
| Business loans | Company, lender, your personal involvement | Key-person insurance |
| Personal guarantees | Who you guaranteed, for what, up to how much | Usually none — high risk |
| Tax | Pending income, property or wealth tax | — |
| Money owed to you | Loans to family or friends, receivables | A written acknowledgement |
Why it matters for heirs
- To decide: in systems where heirs choose to accept, accept up to the net assets, or refuse (Can you refuse an inheritance? Debts, options and timing), the liability map is the basis of the decision.
- To claim: borrower insurance can repay a mortgage — but only if someone knows it exists and files a claim.
- To negotiate: clear information speeds up discussions with lenders.
- To be fair: loans you made to one child may need to be taken into account in the division between siblings — note them.
See the net, not just the gross
OSTREON lets you attach debts — mortgages, loans — to the asset they relate to, so the portal and wealth report show true equity. Add guarantees and money owed to you as their own entries, with documents. Your heirs receive a faithful balance sheet: what exists, what is owed, and what insurance may cover it.
Start your free month →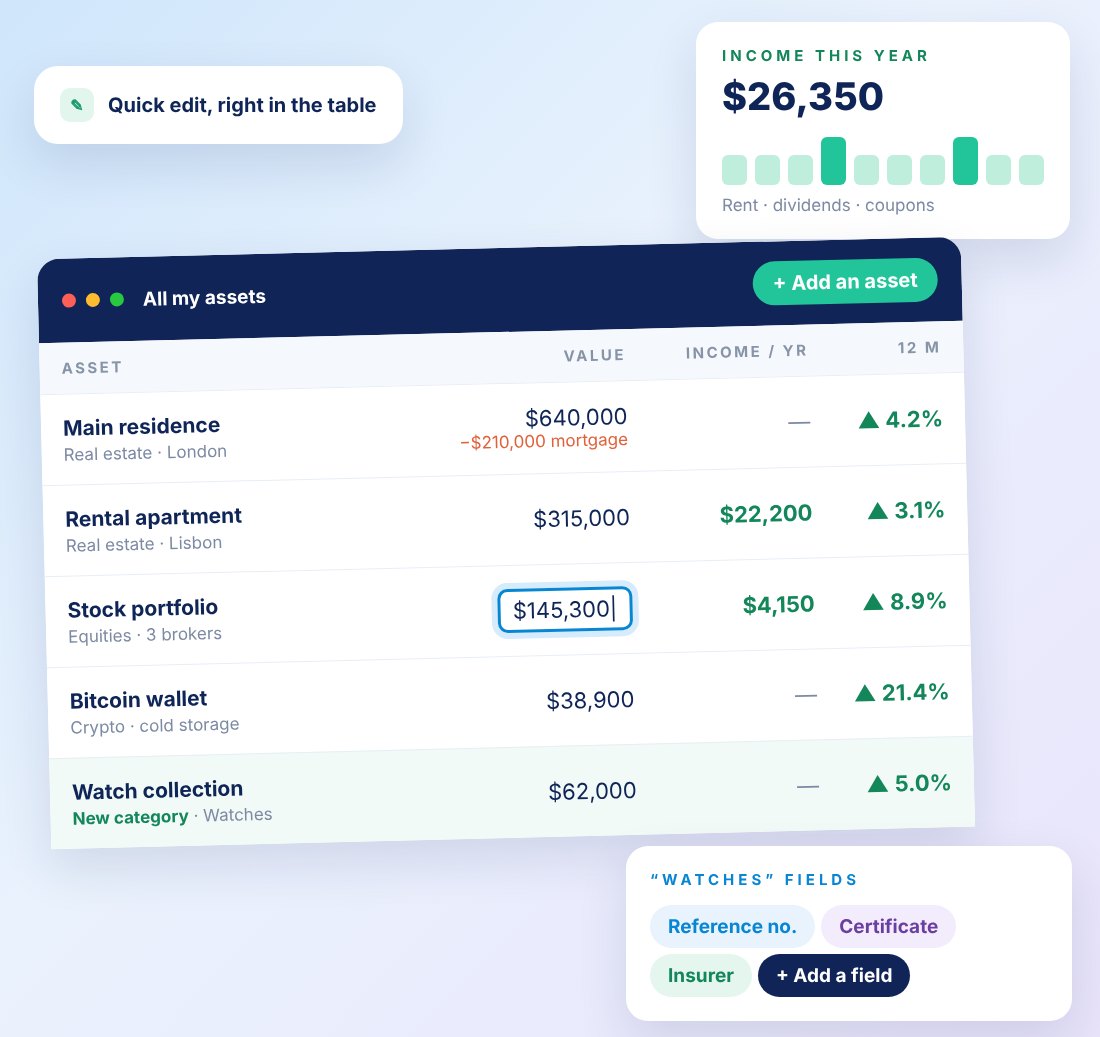
Frequently asked questions
What happens to debts when someone dies?
They generally remain and are paid from the estate before distribution. Depending on the country and the option heirs choose, heirs may or may not be personally liable beyond the estate’s value.
Do children inherit their parents’ debts?
In some civil-law systems, an heir who accepts the inheritance outright can be liable for its debts; accepting up to the net assets or renouncing limits that risk. In common-law systems, debts are generally paid from the estate.
Can borrower insurance repay a mortgage after death?
Often yes, depending on the policy. Heirs need to know the insurance exists and file a claim with the insurer.
Why are personal guarantees risky for heirs?
Because they are often undocumented at home, may be large, and can be enforced against the estate. Record any guarantee you have given.
This article is general information, not legal, tax or financial advice. Rules differ by country and change over time — check with a qualified notary, lawyer or adviser for your situation.